The sum insured
Is it enough to do the job, and not so large that you are insuring a lifestyle you do not have?
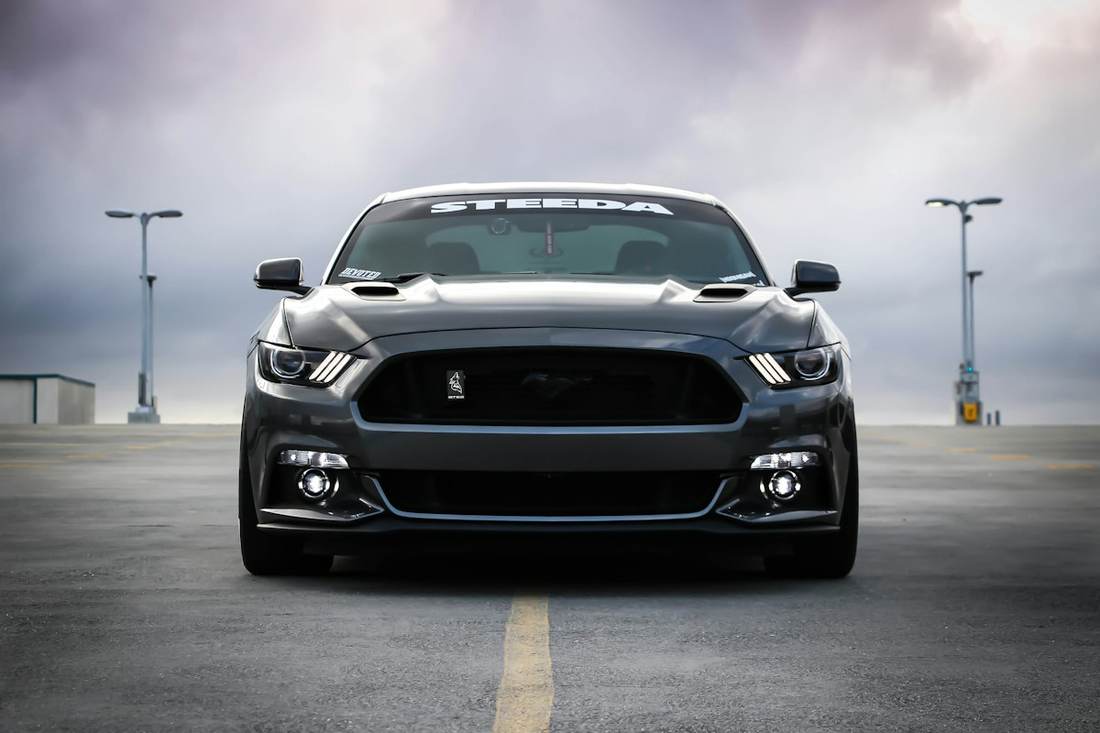
Motor cover should match how the vehicle is used: private errands, a commute, or occasional business trips. We quote third-party, third-party fire and theft, and comprehensive protection, and we explain what an excess, a no-claim record, and a named-driver list do to the contribution. Agreed value is available for cherished vehicles when a market value would not put the same car back in your garage.
Tell us about modifications, the true overnight location, and anyone who will drive even once a month. A claim is harder to support when the person at the wheel was never declared. If you also need cover while a car is being repaired, ask us to show that option on the illustration rather than assuming it sits inside every comprehensive policy.
Nothing on this page starts a policy. Cover begins only on the date printed on a schedule, after you have accepted it and any first contribution has been paid. If a sentence here disagrees with that schedule, the schedule wins.
Is it enough to do the job, and not so large that you are insuring a lifestyle you do not have?
Could you pay it next month without borrowing? A lower contribution is not a saving if the excess is fantasy.
Read them while nothing is wrong. Ask us to restate any sentence that still feels slippery.
Know the mailbox, the photographs you would take, and who in the household can write to us.
Our promise is to make complex insurance language readable, to answer claim questions in writing, and to show the price of cover before you commit.
Leave a note and an advisor will reply by email.
BFDLife began as a promise to explain cover before anyone was asked to buy it. If you are comparing policies today, write down the people who rely on you, the loan you could not clear alone, and the excess you could pay next month without borrowing. Bring that page to hello@bfdwinery.com. We will answer with options, including the option to buy less.